Surgical Robotics Market: Precision, Competition, And The Next Era Of Surgery
The surgical robotics market has evolved from specialized technology into an increasingly integrated component of modern minimally invasive surgery. Early systems focused primarily on surgeon-controlled visualization, instrument manipulation, and precision. Current platforms increasingly combine robotics with advanced imaging, digital workflows, data analytics, and procedure-specific capabilities. According to the U.S. Food and Drug Administration (FDA), robotically assisted surgical devices are used across general, cardiac, colorectal, gynecologic, head and neck, thoracic, and urologic procedures when operated by appropriately trained physicians.
Market expansion is being supported by broader clinical adoption, growing surgeon familiarity, and increasing interest in minimally invasive approaches. Key trends include smaller robotic platforms, single-port architectures, orthopedic robotics, advanced visualization, artificial intelligence, digital surgery, and ambulatory surgical applications. These developments are encouraging healthcare providers to evaluate robotic technologies across a wider range of procedures and clinical settings, supporting sustained surgical robotics market demand.
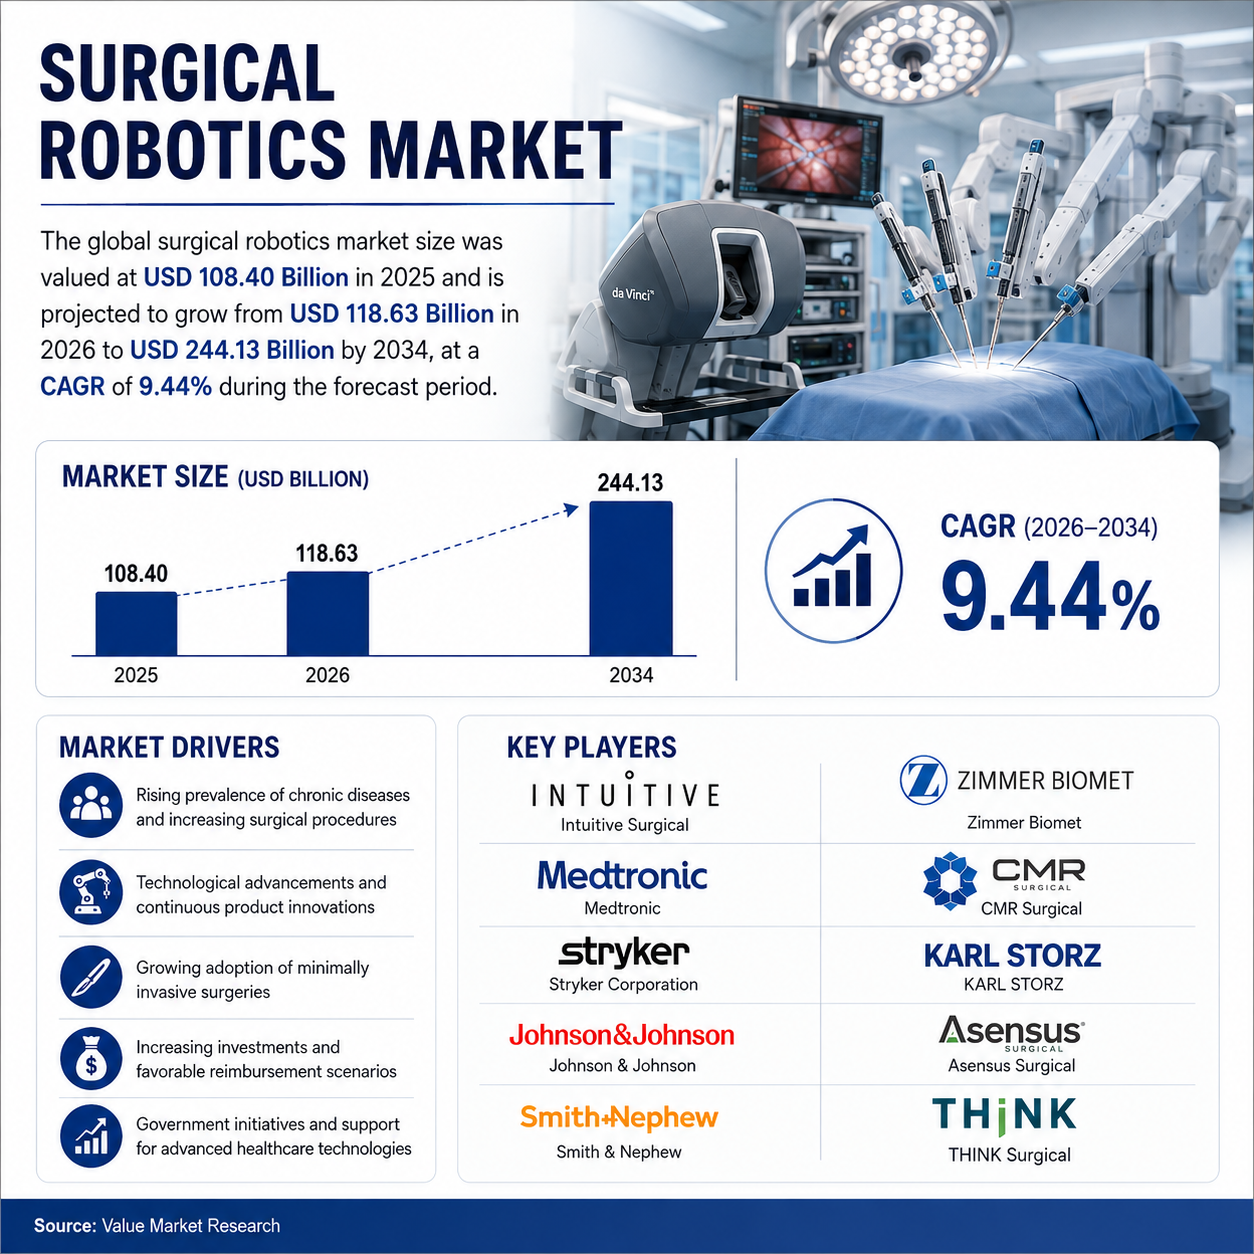
According to Value Market Research, the global demand for Surgical Robotics market was valued at USD 108.40 Billion in 2025 and is expected to generate USD 244.13 Billion by 2034, growing at a CAGR of 9.44% between 2026 and 2034.
Growth drivers include rising demand for minimally invasive procedures, improved visualization, procedural precision, surgeon ergonomics, and technology-enabled clinical decision-making. Healthcare providers are also exploring robotics for complex procedures where dexterity and controlled instrument movement can provide operational advantages. According to the American College of Surgeons (ACS), robotic-assisted surgery remains more widely adopted in the United States and Europe than in many other regions, highlighting substantial international expansion potential.
Training, affordability, interoperability, and operating room infrastructure remain important adoption considerations. AORN emphasizes hands-on training for nurses and surgical technologists because robotic procedures require specialized room setup, docking, troubleshooting, and emergency undocking capabilities. The opportunity therefore extends beyond robotic platforms to instruments, software, simulation, data services, training, and integrated operating room solutions. As healthcare systems seek greater procedural efficiency, technology developers that combine clinical utility with practical deployment models can address expanding demand.
Surgical Robotics Market Recent Developments
Jun 2026: Medtronic completed its acquisition of Scientia Vascular, combining Scientia’s neurovascular access products with Medtronic’s therapeutic technologies. The transaction is designed to provide physicians with integrated access and treatment solutions across the neurovascular workflow, particularly where rapid intervention is critical.
Apr 2026: Medtronic completed its acquisition of CathWorks, adding the FFRangio® System to its cardiovascular intervention portfolio. The technology provides comprehensive physiological assessment of coronary artery disease using a drug-free, wire-free approach.
Jun 2026: Stryker launched the TPX HD power tool, a premium small-bone surgical tool designed for demanding orthopaedic procedures, including total-joint revisions, minimally invasive surgery and oral-maxillofacial procedures. It offers enhanced torque, faster performance, customizable control through I.D. Touch software and specialized attachments for cutting metal and bone cement.
Leading Market Players in the Surgical Robotics Market
The surgical robotics market remains concentrated among established platform providers, while competition is broadening as emerging and niche developers target specialty procedures. Established players account for the majority of commercial activity, emerging players form a growing competitive layer, and niche companies focus on orthopedics, microsurgery, navigation, and modular soft tissue applications. Key players pursue share through new indications, improved ergonomics, smaller footprints, advanced visualization, digital analytics, surgeon training, and broader instrument portfolios. Companies also strengthen installed-base economics through service programs, reusable technologies, and workflow integration. Collaboration is increasingly important. Partnerships with hospitals, universities, technology providers, and surgical societies support evidence generation, education, product development, and market access.
Intuitive Surgical
Intuitive Surgical is positioned as a leading surgical robotics company within the global market. Its portfolio centers on robotic-assisted platforms, instruments, visualization, digital technologies, and procedure support. The company emphasizes precision, minimally invasive workflows, surgeon control, and operating room efficiency. Its broad technology focus supports continued innovation across soft tissue procedures and reinforces its role in the market’s competitive landscape.
Medtronic
Medtronic occupies a major position in the surgical robotics landscape, with a broad medical technology orientation that complements robotic-assisted surgery. Its market positioning emphasizes integrated workflows, precision, digital connectivity, and procedural efficiency. In Jul 2026 Medtronic completed its acquisition of SPR Therapeutics, adding the SPRINT® Peripheral Nerve Stimulation (PNS) system to its neuromodulation portfolio. The technology provides minimally invasive, non-opioid treatment options for chronic and acute pain and is intended to support earlier intervention for patients.
Stryker Corporation
Stryker is an established medical technology participant with strong relevance to robotic-assisted orthopaedic procedures. Its positioning centers on precision planning, image guidance, workflow integration, and technology designed to support surgeon decision-making. In Jul 2026 Stryker launched Mako RPS (Robotic Power System) commercially in the U.S. for total knee replacement, expanding its Mako robotics portfolio into handheld robotics. The system combines robotic execution, intraoperative planning and a handheld power-tool workflow, and is compatible with the Triathlon Total Knee System.
Johnson & Johnson
Johnson & Johnson brings extensive surgical technology expertise to the surgical robotics landscape. In Jan 2025 Johnson & Johnson announced an agreement to acquire Intra-Cellular Therapies, Inc. for approximately $14.6 billion in cash, strengthening its neuroscience portfolio. The acquisition added CAPLYTA® (lumateperone), a once-daily oral medicine approved in the U.S. for schizophrenia and bipolar depression, along with ITI-1284, a Phase 2 asset being evaluated for generalized anxiety disorder and Alzheimer’s disease-related psychosis and agitation.
Smith & Nephew
Smith & Nephew participates in surgical robotics through technology focused on orthopaedic procedures and digitally enabled surgical workflows. Its market positioning emphasizes precision, planning, visualization, and procedural consistency. In Jul 2026 Smith+Nephew received FDA De Novo classification for its TESSA Spatial Surgery System, an AI-enabled platform combining personalized planning, augmented reality, advanced imaging, navigation and real-time tracking for arthroscopic procedures.
Zimmer Biomet
Zimmer Biomet maintains a significant presence in technology-enabled orthopaedic surgery. Its robotics positioning emphasizes surgical planning, precision, digital assistance, and workflow integration. In Apr 2026 Zimmer Biomet and Peritas AI Inc. began a collaboration exploring agentic connected robotics for a more unified operating room. The companies are evaluating how artificial intelligence, workflow software, humanoid robots, surgical robots and surgeons can work together through real-time orchestration.
CMR Surgical
CMR Surgical represents an important emerging participant in surgical robotics, with a strategy centered on modular robotic-assisted surgery. Its positioning emphasizes flexible system architecture, surgeon communication, operating room integration, and digital capabilities. In Feb 2025 CMR Surgical and KEBOMED expanded their existing partnership to bring the Versius Surgical Robotic System to more hospitals in Sweden. The agreement extended their Nordic collaboration, which already covered Denmark, Norway and Finland.
KARL STORZ
KARL STORZ brings extensive expertise in endoscopy, visualization, and operating room technologies to the surgical robotics ecosystem. In Jul 2026 KARL STORZ announced strategic partnerships with Moon Surgical and Sovato in the United States to expand its open surgical-robotics ecosystem. With Moon Surgical, KARL STORZ is combining its 3D visualization and operating-room integration technologies with the Maestro AI-native robotic platform to support minimally invasive surgery.
Asensus Surgical
Asensus Surgical is associated with digital surgery and robotic-assisted technology designed to enhance minimally invasive procedures. Its positioning emphasizes data-driven workflows, surgeon control, visualization, and performance guidance. The company contributes to the market’s broader movement toward digitally connected surgery. Its technology focus supports continued development of intelligent surgical environments where procedural information can improve consistency and workflow management.
THINK Surgical
THINK Surgical focuses on robotic technology for orthopaedic procedures, with an emphasis on planning flexibility and surgeon-directed workflows. Its positioning highlights technology designed to support implant choice, individualized surgical planning, and precise execution. The company contributes to competitive diversification within orthopaedic robotics. Its approach can appeal to healthcare providers seeking adaptable robotic solutions across evolving surgical pathways and implant strategies.